
Specified Private Pension
Enjoy greater flexibility with your pension savings. You can allocate up to 3.5% of your mandatory pension contribution to a specified private pension instead of a collective pension fund.
Enjoy greater flexibility with your pension savings. You can allocate up to 3.5% of your mandatory pension contribution to a specified private pension instead of a collective pension fund.
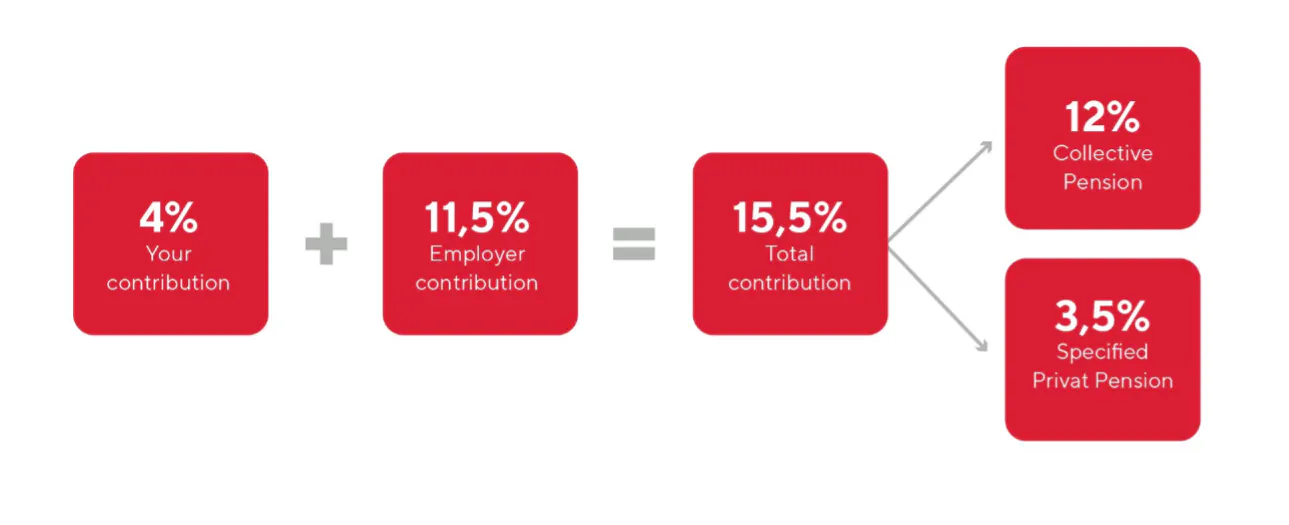
As an employee, part of your salary is paid into mandatory pension savings. This is required by law and amounts to 15.5% of your salary: 4% from you and 11.5% from your employer.
You can choose to allocate up to 3.5% of this contribution into a specified private pension. This is your own private pension, rather than a contribution to a collective pension fund.
If you have already built up a lifelong pension with your mandatory pension fund, specified private pension savings can offer greater flexibility. These savings are your asset. They are inheritable, available from age 62 and protected from seizure if something unexpected happens.
You choose how to invest your specified private pension savings, and which custodian suits you best.
To get started, enter into an agreement with us. Then contact your mandatory pension fund and request that up to 3.5% of your mandatory pension contribution be transferred to us.
Sometimes it helps to talk to someone and seek advise.
